Bank of Korea Starts Second CBDC Test: Why Allowance Usage Can Be Restricted
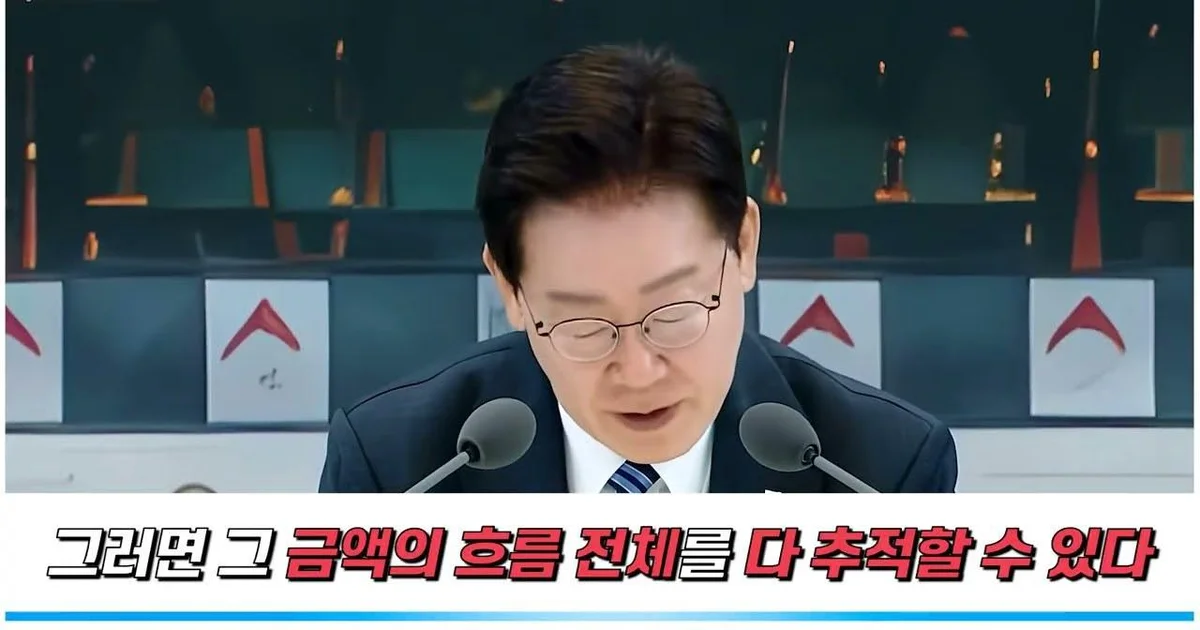
The Bank of Korea will begin its second phase of testing for the introduction of Central Bank Digital Currency (CBDC) in earnest starting in October. This test goes beyond simply checking whether payments can be made and enters a stage of verifying remittance functions in real life, and it is scheduled to be conducted for approximately 500,000 people.
The Light and Shadow of the 'Programmable' Function That Can Designate Allowance Usage
According to the Beomi Ssaem video, CBDC is a digital currency issued directly by the central bank, which is fundamentally different from existing simple payment services such as Samsung Pay. The biggest difference is that the government manages it directly and 'programming' is possible. In other words, specific purposes or conditions can be attached to the currency.
For example, when giving an allowance to a child, it is possible to set restrictions so that it can only be used in specific regions or specific industries (e.g., stationery stores). If set this way, payments cannot be made at places like restaurants that are not designated. One of the main justifications for its introduction is that if this method is applied when the government pays basic pensions, national pensions, voucher cards, or subsidies, it can effectively block fraudulent receipt. This is because the flow of subsidies can be tracked overall, preventing use for purposes other than intended.
Concerns Over Personal Transaction Surveillance and Controversy Over Future Technology
However, these functions simultaneously give rise to concerns about the infringement of individual financial privacy. This is because the ability to restrict the purpose of currency use can, paradoxically, become a means for the government to identify and control individual transaction details and usage patterns in detail. The video mentioned cases such as the United States discussing a CBDC ban law or former President Trump warning about the dangers of CBDC, conveying anxiety about the possibility of control that digital currency may bring.
Predictions regarding the stages of technological development are also a subject of controversy. As an extension of the process of evolving from coins to banknotes, from banknotes to cards, and then to smartphone payments, some even mention implantable chips as the final stage of digital currency. In fact, there is a case in Sweden where technology was introduced to open doors or make payments by implanting microchips in the palm of the hand. As the Bank of Korea's second test is a stage that verifies even remittances in real life, various social discussions that may occur during the transition to a cashless society are expected to continue.
Related Articles
Accountant Sa Gyeong-in, "Exchanging money and time is for fake rich... Real rich people are those who balance them"
BYD Sea Lion 08 priced in the 40 million won range in China... Air suspension and rear-wheel steering come as standard
Kurly to Achieve 1.4 Trillion Won in Revenue in First Half of 2026… Turning Operating Profit Positive through Logistics Efficiency
Low-Sugar and ZERO Jelly Purchases Surge 37.1% While Total Jelly Market Decreases 12.3%
Sokcho Daepo Port Fish Market: 150,000 Won Snow Crab Course Composition and Merchants' Stance
40% Discount on Domestic Agricultural and Livestock Products… Unlimited Chuseok Shopping Benefits with No Limit
Hanasaki King Crab Appears at Noryangjin Fisheries Wholesale Market... Prices for Flounder and Red Sea Bream Rise Ahead of Holidays
Large Eggs 30-pack at 4,940 won, the reason it differs from 7,110 won... Event price lasts until the 24th
Homeplus Bankruptcy Crisis: Why the MBK Partners Acquisition Structure and Unpaid Debts are Key
From Vietnam's VinFast to Saudi Arabia's Ceer, Emerging Nations' Domestic Car Offensives Threaten Hyundai Motor Company
Chuseok Shopping 30% Refund? What to Check Before Combining Receipts
Comments 0